Your browser cannot save progress right now. You can still investigate; keep this tab open or enable local storage to save.
This case has been updated. Compatible choices are kept; revisit the evidence before drawing your conclusion.
01 · The briefing
Begin with the question.
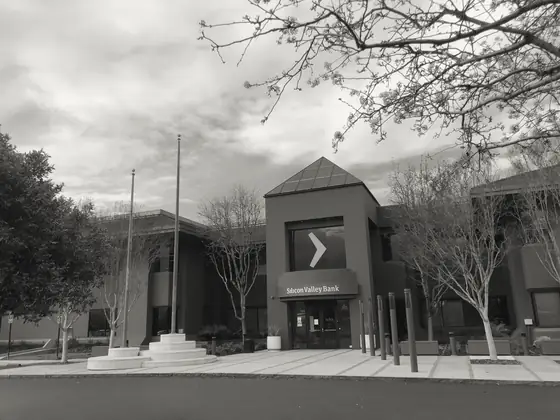
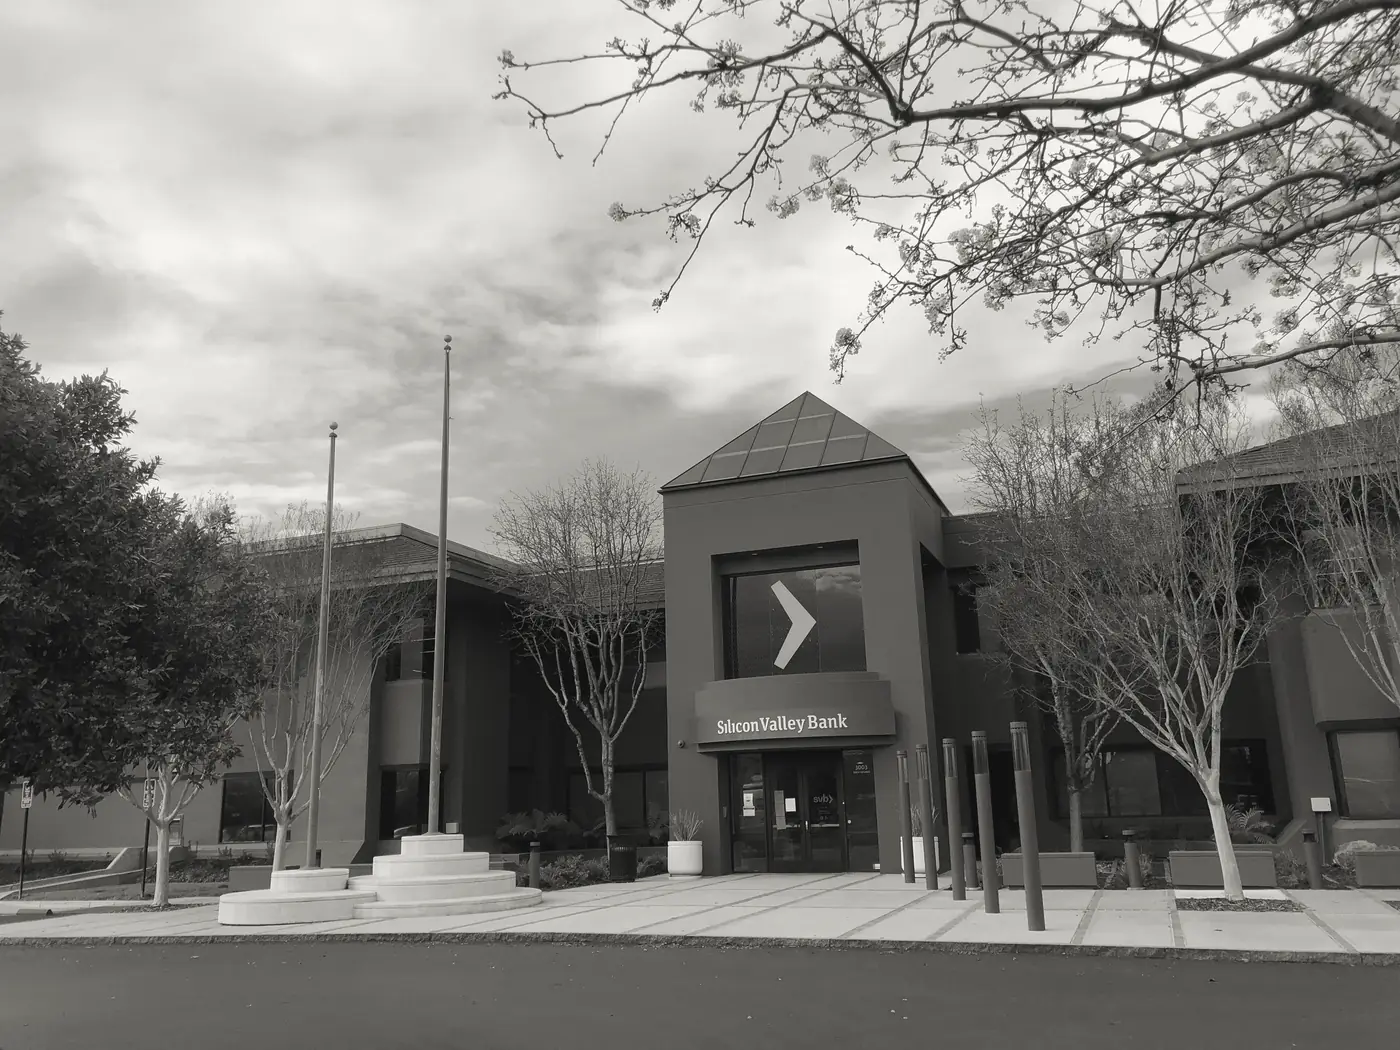
Silicon Valley Bank was the bank of many venture-backed technology companies. At the end of 2022 it had about $209 billion in total assets and about $175 billion in deposits, according to the FDIC. On 8 March 2023 it announced a plan to sell securities at a loss and to raise capital. On 9 March depositors withdrew more than $40 billion, and the bank told supervisors it expected over $100 billion more the next day. The California Department of Financial Protection and Innovation closed the bank on 10 March and appointed the FDIC as receiver. Three explanations are worth testing. One says the bank's loans were failing. A second says a panic spread through social media and investor networks. A third says the bank's own choices about interest-rate risk and funding made it fragile. The Federal Reserve's review of its own supervision of the bank, published in April 2023, points to management failures and to supervisors who did not fully appreciate the vulnerabilities. This case separates the mechanisms the record supports: losses on the securities, a deposit base that could leave at once, and management's handling of rate risk.
The timeline
The bank begins a strategy to remove interest-rate hedges as market rates rise, according to the Federal Reserve review.
The bank has about $209.0 billion in total assets and $175.4 billion in deposits, and about 94 percent of its deposits are uninsured.
The bank announces a plan that includes selling $21 billion of available-for-sale securities at a $1.8 billion after-tax loss and raising $2.25 billion of capital.
Deposit outflows exceed $40 billion, and management expects over $100 billion more on 10 March; the review says this outflow represented roughly 85 percent of the deposit base.
The California regulator closes the bank and appoints the FDIC as receiver.
The FDIC says insured depositors will have full access to their insured deposits no later than the morning of 13 March.
The Federal Reserve publishes its review of its own supervision and regulation of the bank.
A researched reconstruction for learning. These reasoning steps simplify a complex record; no score can capture the full history.
02 · The evidence
What does the record show?
Read each exhibit before settling on an explanation. The source links below every exhibit lead to the record behind it.
Exhibits reviewed 0 of 5
Safe credit, long duration
The Federal Reserve review describes a large held-to-maturity portfolio, mostly government-agency mortgage securities. It calls them low risk from a credit perspective, but they paid a return fixed at purchase. At year-end 2022 the held-to-maturity portfolio had a weighted-average duration of 6.2 years, and most of it consisted of agency mortgage securities with maturities of ten years or more. This establishes that the main risk was duration, not default. It does not give the total unrealized loss across the portfolio, which the review shows only in a chart.
Source record s1federalreserve.gov
Deposits that were mostly uninsured
The review reports that about 94 percent of total deposits were uninsured at year-end 2022, against 41 percent for large banking organizations. It says highly correlated withdrawals from a concentrated network of venture investors and technology firms, fueled by social media, removed uninsured deposits in a coordinated manner at an unprecedented rate. The bank lost over $40 billion on 9 March and management expected over $100 billion more on 10 March, an outflow the review puts at roughly 85 percent of the deposit base. This establishes concentration and speed. It does not establish that the same depositors would have stayed if their deposits had been insured.
Source record s1federalreserve.gov
Hedges removed and interest-rate limits breached
The review says management took a short-term view of interest-rate risk through net interest income, began removing interest-rate hedges in March 2022, and had breached its long-term interest-rate risk limits on and off since 2017. It says the hedges were designed to protect against rising rates, and that the bank saw rising rates as an opportunity to take profits on them. This establishes that management reduced its protection against rising rates. It does not establish what management expected rates to do, and it is the review's assessment rather than a trading record.
Source record s1federalreserve.gov
The sequence from 8 to 10 March
The review describes the 8 March restructuring: the sale of $21 billion of available-for-sale securities at a $1.8 billion after-tax loss, a planned increase in term borrowing of $15 billion to $30 billion, and a $2.25 billion capital raise. It says outflows exceeded $40 billion on 9 March, and that the bank told supervisors it expected over $100 billion more on 10 March. It also says the bank did not have enough cash or collateral to meet the outflows. This establishes how fast the run moved. It does not show how much the announcement mattered compared with the social-media spread, which the review treats as interacting.
Source record s1federalreserve.gov
What the FDIC said at closing
The FDIC release says the California regulator closed the bank on 10 March and the FDIC was appointed receiver. It gives total assets of about $209.0 billion and deposits of about $175.4 billion at 31 December 2022, and says the amount of deposits above the insurance limits was undetermined at closing. It says the FDIC created a Deposit Insurance National Bank of Santa Clara to protect insured depositors, that uninsured depositors would receive an advance dividend and a receivership certificate, and that the FDIC as receiver will retain the assets for later disposition. This establishes the legal sequence. It does not establish the value of the assets.
Source record s2fdic.gov
03 · Your reasoning
Follow the strongest explanation.
Choose an interpretation, then compare it with the evidence. You can revise your choice. The goal is understanding, not a perfect score.
04 · The findings
The chain behind the outcome.
Your notebook
Case report
Next in history & systems: Which test was actually run?
The record points to a failure in which safe-looking assets became fragile through their interaction with funding. Silicon Valley Bank's held-to-maturity portfolio was mostly government-agency mortgage securities that carry little credit risk. With a weighted-average duration of 6.2 years at year-end 2022, its market value fell as rates rose. The Federal Reserve review says the bank took a short-term view of rate risk through net interest income, removed interest-rate hedges from March 2022, and had breached its long-term interest-rate risk limits on and off since 2017. Funding was the second fault line. About 94 percent of deposits were uninsured at year-end 2022, and withdrawals of more than $40 billion on 9 March left the bank without enough cash or collateral to meet the expected further outflows. The California regulator closed the bank on 10 March, and the FDIC became receiver. The review ties the failure to the combination of interest-rate risk and a concentrated deposit base, and finds that supervisors did not fully appreciate the vulnerabilities. It does not describe fraud. The lesson is that a security's credit safety did not protect the bank from losses on rate changes, and that a concentrated funding base could turn those losses into failure within days.
Contributing causes and conditions
- The bank held long-dated, fixed-return government-backed mortgage securities whose market value fell as interest rates rose.
- Management focused on near-term net interest income, removed interest-rate hedges from March 2022, and breached its long-term interest-rate risk limits on and off since 2017.
- About 94 percent of deposits were uninsured at year-end 2022, and many were concentrated among venture-backed technology companies.
- The bank announced its restructuring plan on 8 March, and withdrawals accelerated the next day.
- Withdrawals of more than $40 billion on 9 March, with over $100 billion more expected on 10 March, which the bank did not have enough cash or collateral to meet
- Supervisors did not fully appreciate the extent of the vulnerabilities, according to the review.
OutcomeSilicon Valley Bank failure (2023)
Take the method with you
- Credit safety and interest-rate safety are different: an asset with little default risk can still lose market value when rates rise, so test both.
- A funding base that is concentrated and mostly uninsured can change within hours, so the speed of possible withdrawals belongs in the risk analysis.
- When a firm removes protections to protect short-term profit, ask which risk its metrics are hiding, and check the measure of longer-term exposure.
You can read findings at any time. Exploring every reasoning step marks this case as complete in your notebook.
The open record
Sources & further reading
Read the original record and its scope before relying on a conclusion. Source references support the exhibit summaries; Faultory’s reasoning prompts are editorial reconstructions.
- s1
- s2
Written and curated for Faultory by Yunus Emre Vurgun, with AI-assisted research and drafting. Sources and interpretations can need correction. Read our editorial standards or report an issue.
Keep investigating